Digital banking · Application and service design · Launched
Completed at Washington Mutual, whose banking operations were later acquired by JPMorgan Chase in 2008. Acquisition details.
Opening a bank account online could still mean waiting for the mail.
A traditional signature card created a dependency that could delay account opening for days. Customers could begin the process digitally, but a piece of paper still stood between them and an open account.
I led the application redesign and co-designed the process flow behind it. The work brought together two connected opportunities: simplify the application customers completed and remove the signature-card handoff that held up the service.
Looking beyond the application
A simpler application could help customers move through the online experience. But the time they spent completing it was only part of the problem. The signature-card requirement added a separate wait, outside the interface.
That made the sequence of the service central to the design challenge. We needed to consider how the bank captured a signature and when that step needed to happen in relation to opening the account.
My role connected those two levels of the experience. I led the work on the application while helping shape a process that could support a faster path to an open account.
Changing when the signature was captured
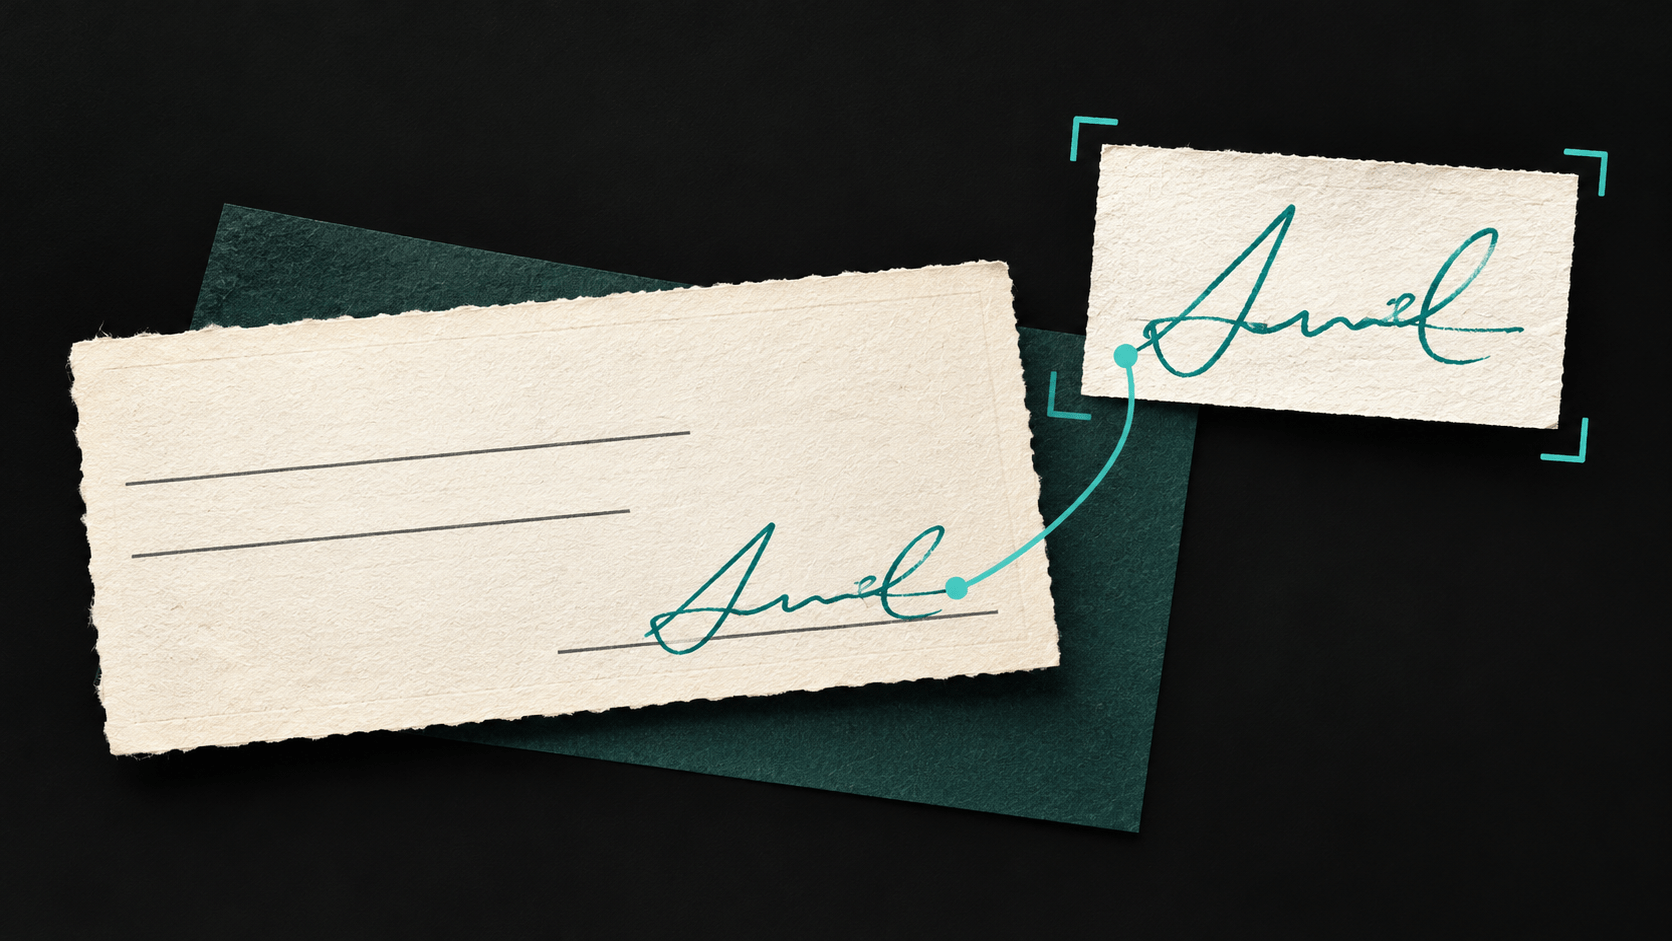
The redesigned service allowed customers to open their account before the bank received a signature sample.
After funding the account, the customer used a specially designed first check. Once that check was written and processed, it was scanned and used as the account’s signature sample.
The bank still collected the signature. Moving that step later in the sequence meant customers no longer had to mail a separate card and wait for it to arrive before their account could be opened.
That change gave the application redesign a simpler service flow to support. The online experience could carry customers through account opening, with the signature captured afterward as they began using the account.
Making a faster experience tangible
Alongside the service change, we simplified the application itself. In our testing, the application was completed in five minutes or less. The launch campaign promoted a seven-minute application, giving customers a clear expectation for the time they would spend online.
The two improvements addressed different parts of the experience. The application redesign reduced the effort of applying. The signature process removed a dependency that could add days to opening the account.
The bank announced the service on May 11, 2006, describing online approval and account opening with the signature sample collected afterward through the customer’s first processed check. Launch announcement.
Part of a growing online business
The redesigned experience operated within a growing online banking business. In Q2 2007, the bank reported 89,000 net new checking accounts through its online channel—twice the number opened through that channel in Q2 2006. Quarterly results.
That figure provides context for the scale and growth of the channel; it does not isolate the impact of this redesign. The project’s direct contribution was a simpler application and an account-opening process freed from the mailed signature-card dependency.
For me, this project illustrates why application design and service design belong together. Understanding the process behind the screens revealed an opportunity to change the experience more fundamentally. By changing when the signature was captured, we removed a wait that a faster form alone could never resolve.